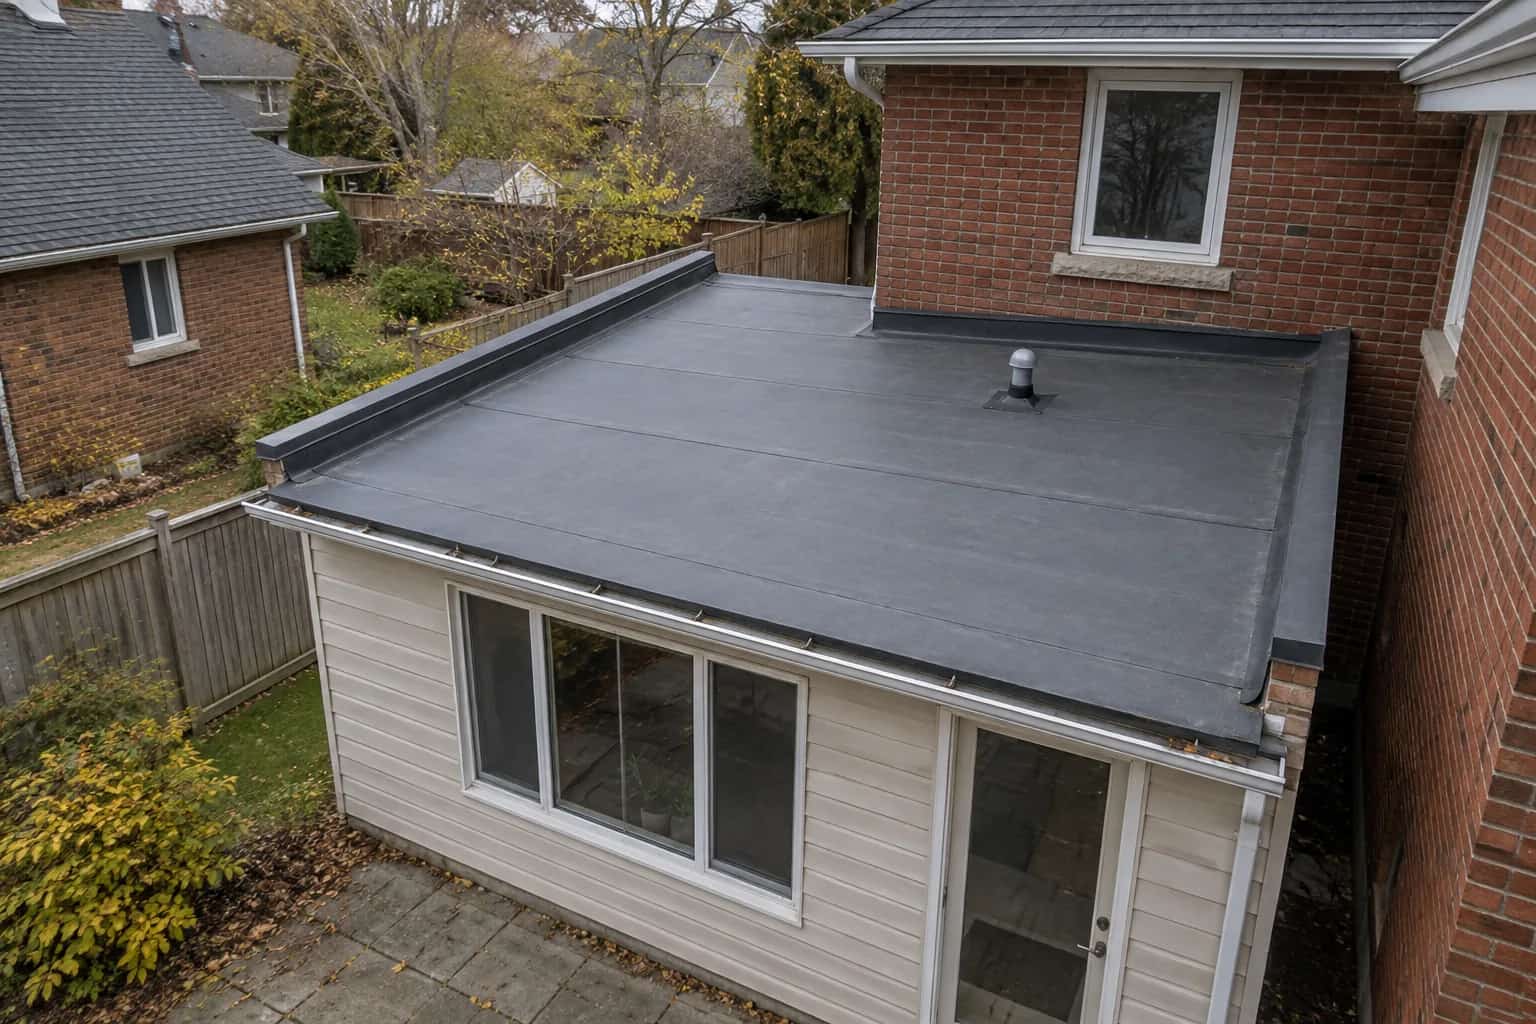
Yes: contact your home insurer or broker before a significant roof replacement or alteration. Send the actual work description, not just the words new roof. Replacing shingles on the same house is a different proposal from adding a dormer, changing the structure or leaving the building unoccupied during a larger renovation.
The purpose is to establish what the existing policy covers during the work and what information or changes the insurer requires. Do not assume either that every reroof needs a new policy or that a familiar contractor makes the notification unnecessary.
The owner's draft email says replacing roof, same house. Dave points to the new skylight and the raised section on the drawing. "Same address," he says. "A few details have ambitions." They attach the scope rather than asking the broker to guess what the two words roof replacement include.
Describe the Change in Ordinary Building Terms
A useful notice includes the address, expected start and duration, contractor, material being removed, proposed covering and any changes to structure, openings or use. Mention solar work, new skylights or an addition where they are part of the project. Attach the scope if it makes the explanation clearer.
The federal Office of Consumer Affairs renovation guidance advises discussing additional insurance needs with the insurer. The Insurance Bureau of Canada's renovation guidance also notes that coverage terms can change and additional construction coverage may be needed.
Ask the insurer to respond to this project, with its stated scope and timing. A general explanation of renovation insurance does not confirm the position for your address.
Occupancy Can Change the Conversation
Tell the insurer if the household intends to move out, if the building is already empty or if services will be interrupted. Use the policy's own definitions and obtain an explanation rather than guessing whether a short absence counts as vacancy or unoccupancy.
Suppose a family plans to stay with relatives while the roof and upstairs rooms are rebuilt. The original estimate says two weeks, but the opening reveals structural work. Notify the insurer of the changed duration and scope. The information supplied before the job may no longer describe the risk halfway through it.
The same principle applies if a property is rented. Identify who occupies it, how tenants will be notified and whether they need to speak to their own insurer about belongings or temporary arrangements. The owner's building policy should not be treated as a substitute for everyone's separate coverage.
The project is extended when an opening reveals more work. The owner updates the insurer with the revised scope and dates while the contractor updates the estimate. Keeping those conversations together prevents the policy file describing a small job that ended last week while the real house is still under construction.
Ask About the Work Period and the Finished Roof
Separate the discussion into two stages. During construction, ask about damage to the existing building, materials at the site, weather exposure and any required conditions. After completion, ask what records are needed to update roof age, material or the home's description.
A contractor's liability policy serves a different purpose from your own property coverage. Request and check the contractor's insurance, but do not assume it automatically pays for every event affecting the house. Our contractor insurance guide explains that separate verification.
If a premium adjustment or endorsement is proposed, get the amount, effective date and conditions. Do not budget on a promised discount for a newer roof or an impact rating until the insurer confirms it for the actual product and policy.
At completion, the homeowner is tired of forms and keen to reclaim the driveway. Mike puts the insurer's requested documents in the handover list with the warranty papers. Finishing the last email is less memorable than the new roof, but it is easier now than reconstructing the project years later.
Tell the Insurer What Changes at Each Stage
Scope, contractor, dates and occupancy plan.
Before work
Scope, contractor, dates and occupancy plan.
During work
Changed duration, exposed areas and revised construction.
At completion
Actual materials, invoice and requested records.
Separate policies
Owner coverage and contractor liability answer different questions.
Keep One Clear Confirmation
After the conversation, send or retain a concise written summary of the work, occupancy plan, dates and insurer's requirements. Save any endorsement and the contact who handled the review. Ask which changes would require another update.
Give the contractor relevant site requirements without handing over unnecessary personal policy information. If an inspection or temporary-protection condition affects the work, make sure it is reflected in the project plan rather than stored only in an email to the broker.
At handover, submit the requested invoice, product information and completion records. Keep the roof record current. A well-described project makes later questions about the roof's age and construction much easier to answer, and avoids having to explain after a loss that the work became rather larger than the insurer was told.