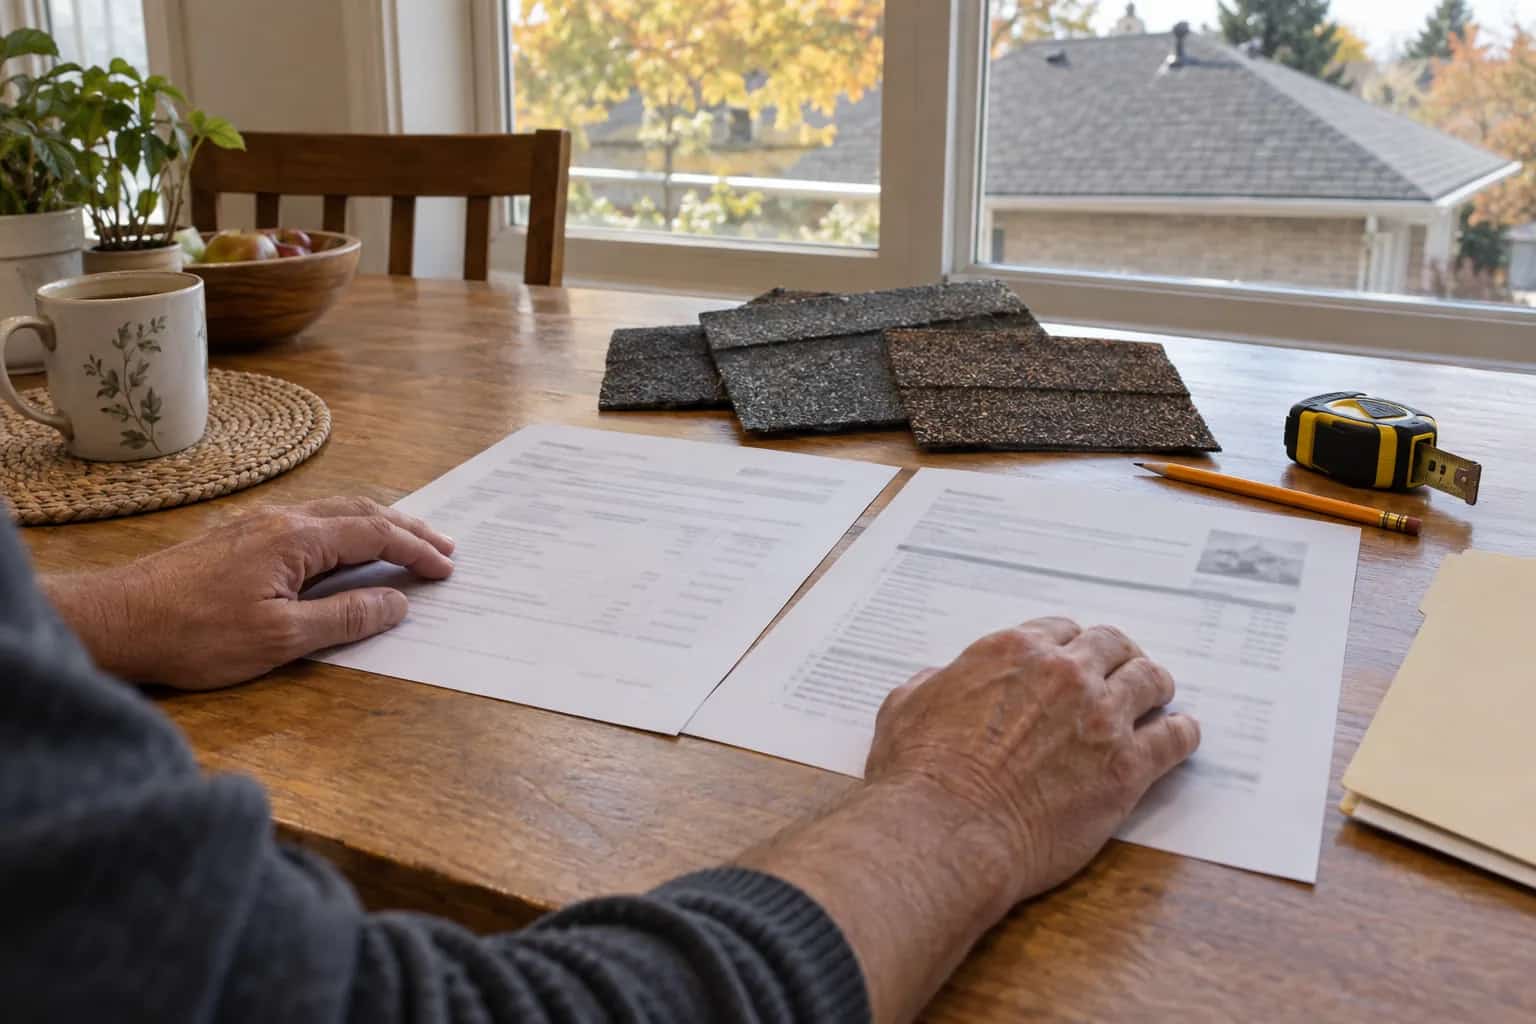
The roof quote is clear. The financing offers are less helpful: one advertises a monthly payment, another offers a line of credit, and neither shows what you will still owe five years from now. Compare the same amount over the same repayment period before choosing the smallest payment.
Start with the roof work you actually need. Keep optional upgrades separate, include known taxes and allowances, and decide how much cash you can contribute without leaving the household unable to handle another ordinary repair. A lender's approved limit is not your roofing budget.
At the table, the homeowner slides the smallest monthly number toward Mike. He turns the page over looking for the end date. "This one tells us how to begin paying. Where does it tell us when we stop?" The kettle clicks off while they find the repayment illustration. The shingles have suddenly become the less complicated purchase.
Three Products That Can Look Alike on a Brochure
A personal loan generally advances an agreed amount with a repayment schedule. A personal line of credit lets you borrow within an approved limit, repay and borrow again. A home equity line of credit, or HELOC, also offers revolving credit, but your home secures the debt. Those differences matter more than whether a lender calls the product a renovation solution.
The Financial Consumer Agency of Canada explains HELOC borrowing, including variable rates, possible setup fees and the risk attached to using the house as security. If required payments cover only interest, the borrowed principal does not shrink. An apparently comfortable payment may therefore be a holding pattern rather than a repayment plan.
Ask each lender for its disclosure and an illustration using your intended repayment schedule. Include the interest rate, whether it can change, fees, optional products and any cost of paying early or closing the account. Separate a promotional rate from the rate and conditions that follow it.
Compare the Debt at the Same Finish Date
Use the same roof scope and cash contribution.
Same principal
Use the same roof scope and cash contribution.
Same finish date
Compare the outstanding balance at an identical date.
All costs
Include interest, setup charges and optional products.
Changed conditions
Check variable rates and early repayment terms.
Put an End Date Beside the Payment
Suppose you borrow $12,000 for an agreed roof scope. Ignoring interest and fees purely to show the principal arithmetic, paying off that amount over 60 months requires $200 of principal per month. A $100 monthly payment cannot retire the same principal in five years, even before borrowing costs enter the picture.
That is not a quotation or a suggested budget. It is a quick way to challenge a comparison that uses a five-year loan beside an interest-only minimum payment. Ask for the remaining balance at the same date under both offers. The difference may be the most useful number on the page.
For a variable-rate option, also request an illustration at a higher rate. Keep your planned payment unchanged in one version so you can see what happens to the payoff date; in another, keep the payoff date unchanged and look at the payment required. Neither predicts rates. Both show what the household would have to absorb.
The household keeps the more expensive shingle option pencilled in, then removes it from the borrowing comparison. That does not reject the upgrade. It stops an extra product from masquerading as a better financing deal. Mike puts the two identical base scopes side by side: "Now the lenders are answering the same question."
Check When the Borrowing Starts
A roofer may require payments at agreed milestones while a lender advances money on a different timetable. Establish who receives the funds, when interest begins and whether you must borrow the entire amount immediately. Confirm how cancelled work, a lower final invoice or an approved change order affects the financing arrangement.
Do not treat lender approval as confirmation that the roofing scope is sound. Use the quote comparison guide first. Likewise, a financing offer does not replace the contract's payment schedule. The two documents should describe a workable sequence together.
One offer still looks attractive, but only if the family makes more than its minimum payment. They write that intended payment on the page rather than leave it as a good intention. Good intentions are excellent at surviving until the washing machine breaks.
Leave Room for the Next Roof Decision
Ask how an extra principal payment works and how you obtain the balance needed to close the account. If you expect to sell before the debt is repaid, discuss that scenario explicitly, especially with borrowing secured against the property.
The practical finish is one sheet showing amount borrowed, cash fees, scheduled payments, balance at your chosen date and total cost under the stated assumptions. If an offer cannot be explained on that basis, get the missing information before signing. For future maintenance, a separate roof reserve can help make the next decision less hurried.